What zero difference means
The adjusted bank and ledger agree mathematically. Timing items still need support, subsequent-clearance checks and review.
Margin Max / Financial & operating control
Bridge the bank statement to the ledger and assign the outstanding items.
Worked example · Illustrative balances and timing items demonstrate the reconciliation structure. Statement $249,500 + deposits $18,000 − checks $6,500 = adjusted bank and GL cash $261,000.
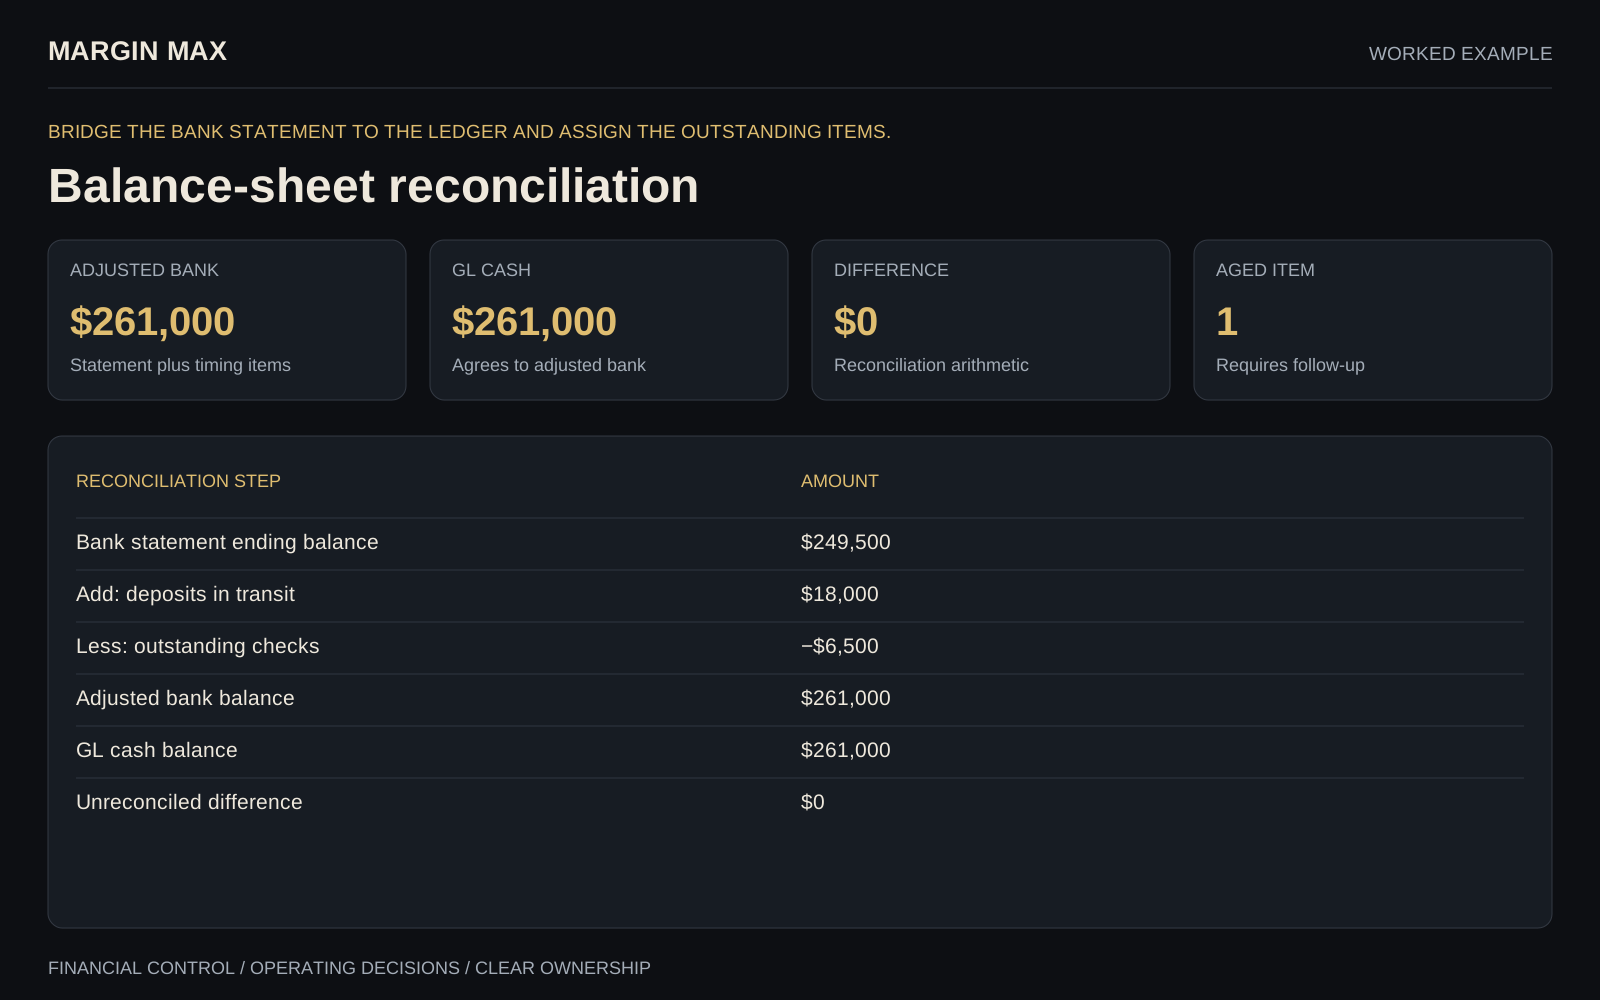
| Reconciliation step | Amount |
|---|---|
| Bank statement ending balance | $249,500 |
| Add: deposits in transit | $18,000 |
| Less: outstanding checks | −$6,500 |
| Adjusted bank balance | $261,000 |
| GL cash balance | $261,000 |
| Unreconciled difference | $0 |
| Item | Amount | Support / aging | Owner | Next step |
|---|---|---|---|---|
| Deposits in transit | $18,000 | Two deposits; 2 business days | AR lead | Match to subsequent bank activity |
| Outstanding checks | $6,500 | $4,500 at 35 days; $2,000 at 7 days | AP lead | Confirm aged check status before reissue |
The adjusted bank and ledger agree mathematically. Timing items still need support, subsequent-clearance checks and review.
Illustrative preparer: staff accountant. Reviewer: Controller. The aged $4,500 check remains open for follow-up; no actual sign-off or clearance is asserted.